By YoungAmericansInsurance.com Editorial Team
Created on
· Last updated on
There is no single insurance company that is cheapest for every young driver. Price can depend on age, driving experience, ZIP code, vehicle, household arrangement, driving record, coverage selections, deductibles, available discounts, and the insurer evaluating the application.
For many teens and young adults, an important comparison is the cost of joining an eligible household policy versus purchasing a separate policy when both arrangements are available. Equivalent quotes are easier to evaluate when they use the same drivers, vehicle, coverage limits, deductibles, optional coverages, and payment assumptions.
YoungAmericansInsurance.com publishes independent insurance information and provides access to third-party quote options on selected pages. Final pricing, eligibility, underwriting, coverage, and policy terms are determined by the insurer or licensed provider responsible for the policy.
Key takeaways
- Insurance prices can differ between insurers even when the applicant and coverage selections are similar.
- Household and separate-policy arrangements can be compared when both are permitted by the insurer and circumstances.
- Good-student, driver-training, student-away, multi-vehicle, low-mileage, and telematics programs may be available depending on the insurer and state.
- Quotes are more directly comparable when drivers, vehicles, limits, deductibles, optional coverages, and payment assumptions are kept consistent.
Household vs. Separate Policies for Young Drivers
When permitted, adding a young driver to an existing household policy can be useful to compare with a separate policy. Household policies may already qualify for multi-vehicle or multi-policy discounts, while a separate policy may produce a different result because of vehicle ownership, residence, household structure, insurer rules, or selected coverage.
Neither arrangement is automatically less expensive. The more useful comparison is the total policy cost using substantially equivalent liability limits, physical-damage coverage, deductibles, optional coverages, drivers, and payment terms.
| Young Driver Situation | Useful Comparison | Information to Confirm |
|---|---|---|
| Age 16–17 and living with parents or guardians | Compare an eligible household-policy arrangement using accurate driver and vehicle information. | Driver assignment, available discounts, coverage limits, and household-driver requirements. |
| Age 18–20 with a personally owned vehicle | Compare household and separate-policy pricing when both arrangements are permitted. | Vehicle ownership, residence, insurer eligibility rules, limits, deductibles, and total policy cost. |
| Age 21–24 with several years of driving experience | Different insurers may price the same driver differently, so renewal pricing can be evaluated against other available quotes. | Driving record, prior coverage, mileage, vehicle, discounts, selected limits, and deductibles. |
| College student living away from home | Use accurate school, residence, vehicle-access, and garaging information. | Whether a student-away program is available and what eligibility or documentation rules apply. |
| Newly licensed driver without a household policy | Compare separate-policy quotes using consistent driver, vehicle, coverage, and effective-date information. | Initial premium requirements, coverage effective date and time, limits, deductibles, and policy terms. |
Insurers may have different rules for household members and regular vehicle users. Accurate driver and household information helps the provider evaluate the application using the information actually associated with the risk.
Ways Young Driver Insurance Costs Can Be Lower
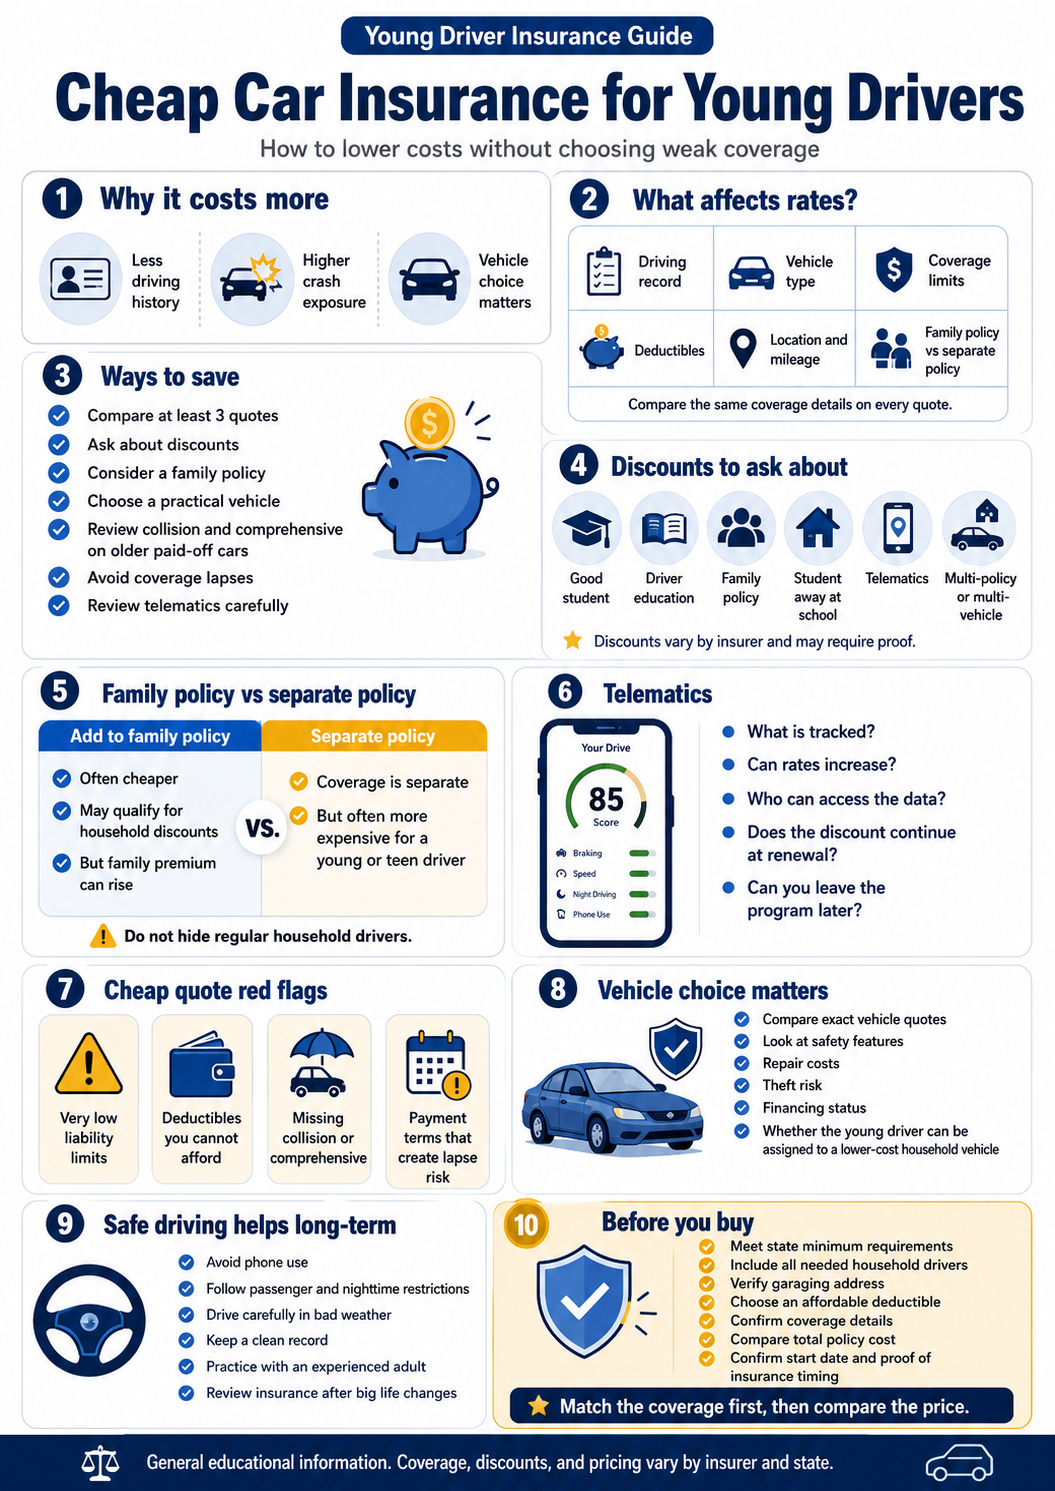
Young-driver insurance prices can reflect several factors, including insurer pricing, household arrangements, vehicle choice, eligible discounts, selected coverage, deductibles, driving history, mileage, and prior insurance history.
A lower premium can come with other differences. A household policy can increase the household’s total premium, an applicable higher deductible increases the policyholder’s portion of an eligible covered loss or reduces the insurer’s payment according to the policy, and telematics can involve collection of driving data. Different limits or optional coverages can also change the protection provided by the policy.
Use equivalent quote inputs
Matching drivers, vehicles, coverage limits, deductibles, optional coverages, and payment assumptions makes price differences easier to interpret.
Verify discount eligibility
Discount availability, documentation requirements, and renewal rules vary by insurer and state.
Vehicle choice affects pricing
Vehicle value, repair costs, theft experience, performance, safety equipment, model year, trim, and insurer loss experience can affect vehicle-related pricing.
Young driver cost checklist
- Compare multiple quotes using substantially the same policy details.
- Compare household and separate-policy arrangements when both are available.
- Confirm documentation requirements for student, training, low-mileage, student-away, or other available discounts.
- Driving record and prior coverage history can affect pricing or eligibility depending on the insurer and state.
- Compare the deductible amount together with the premium and coverage provided.
- Compare the complete policy-term premium and applicable billing charges rather than only the initial payment.
- Confirm that replacement coverage is bound and that its effective date and time have begun before driving or ending prior coverage.
Discounts and Programs Available to Some Young Drivers
Discount availability, eligibility, documentation, and pricing effects vary by insurer and state. The examples below are programs that may be available rather than benefits every young driver will receive.
| Discount or Program | Who It May Apply To | What Can Vary |
|---|---|---|
| Good student | Eligible students who meet the insurer’s academic requirements. | Age limits, enrollment requirements, GPA standards, and required documentation. |
| Driver education or approved training | Young drivers completing a qualifying course where the insurer or state recognizes the program. | Approved courses, certificates, age limits, and state rules. |
| Student away at school | Eligible students living away from home without regular access to a covered household vehicle. | Distance, enrollment, residence, vehicle access, and insurer eligibility rules. |
| Multi-vehicle or multi-policy | Households with multiple eligible vehicles or other qualifying policies with the same insurer. | Eligible policy types, vehicles, household structure, and the insurer’s discount rules. |
| Low mileage | Drivers meeting an insurer’s mileage requirements. | Mileage thresholds, verification method, and frequency of review. |
| Telematics or usage-based insurance | Drivers participating in an insurer’s eligible driving-data program. | Data collected, rating method, state rules, participation terms, and whether driving results can increase or decrease pricing. |
NAIC guidance explains that usage-based insurance can involve driving information such as mileage, time of day, location, acceleration, braking, cornering, and other vehicle or driving data. The information used and its effect on pricing depend on the insurer, program, and applicable state rules. [1]
Vehicle, Coverage, and Deductible Choices
The vehicle assigned to a young driver can affect insurance pricing. Insurers may consider vehicle value, repair or replacement cost, theft experience, performance characteristics, safety equipment, model year, trim, and their own claims experience with similar vehicles.
Vehicle-specific pricing can be easier to evaluate using the exact year, make, model, trim, and VIN when available. Our analysis of vehicle and insurance factors for teen drivers looks at safety recommendations, model years, loss experience, and vehicle characteristics separately from an individual insurance quote.
| Policy or Vehicle Decision | Possible Pricing Effect | Coverage or Eligibility Difference |
|---|---|---|
| Higher collision or comprehensive deductible | A higher deductible may reduce the premium. | The policyholder’s portion of an applicable covered loss is higher. |
| Policy without collision or comprehensive | A policy omitting physical-damage coverage may have a lower premium than one that includes those coverages, depending on other rating factors. | The insured vehicle generally would not have collision or comprehensive protection for losses those coverages would otherwise address. |
| Collision and comprehensive coverage | Including collision or comprehensive coverage can increase the premium compared with otherwise similar coverage that omits it. | A lender or lessor may require collision and comprehensive under a finance or lease agreement. |
| Higher liability limits | Higher selected limits can increase the premium. | Lower limits reduce the maximum amount available under the policy for an eligible liability claim. |
| Performance, luxury, or modified vehicle | Certain vehicles may be rated differently because of value, performance, repair costs, equipment, or insurer loss experience. | Eligibility and underwriting treatment depend on the insurer, vehicle, modifications, and state rules. |
An applicable auto insurance deductible represents the policyholder’s portion of an eligible covered loss or reduces the insurer’s payment according to the policy.
Theft, vandalism, hail, fire, animal damage, and certain other covered non-collision losses generally fall under comprehensive coverage for non-collision losses , subject to the policy terms, exclusions, and applicable deductible.
A lower premium can result from different liability limits, deductibles, optional coverages, discounts, or other rating factors. The NAIC consumer shopping tool recommends looking at coverage, deductibles, available discounts, and payment options when evaluating auto insurance. [2]
How to Compare Young Driver Insurance Quotes
Quotes that use different drivers, vehicles, liability limits, deductibles, optional coverages, mileage assumptions, or policy terms are not directly coverage-equivalent. Keeping the underlying information consistent makes price differences easier to evaluate.
A planning estimate for auto insurance costs can help organize expected expenses before personalized insurer quotes are available. The calculator is an educational planning tool rather than a guaranteed insurance quote.
Information commonly used for auto insurance quotes
- Driver information requested by the insurer or quote provider.
- Accurate driving and prior-insurance history.
- Exact vehicle year, make, model, trim, registration information or VIN when requested.
- Correct garaging address and realistic annual mileage.
- Desired liability limits and optional coverages.
- Collision and comprehensive deductibles.
- Documentation needed for potential student, training, mileage, or other discounts.
- Requested policy effective date and preferred billing frequency.
The process of comparing car insurance quotes for young drivers is more meaningful when driver information, vehicle details, coverage, deductibles, and other quote inputs are consistent. The NAIC auto insurance shopping tool also identifies driver, household, vehicle, mileage, garaging, prior-insurance, coverage, and deductible information that insurers may use when preparing a quote. [3]
Policy Cost, Billing, and Coverage Start Dates
The amount required initially is only one part of the policy cost. Policy-term premium, installment charges, recurring payments, applicable fees, coverage selections, and cancellation provisions can all affect the total amount paid.
Billing structure is separate from insurance coverage. A monthly installment schedule changes how the premium is paid; it does not define the liability limits, deductibles, exclusions, collision coverage, or comprehensive coverage contained in the policy.
Initial amount
The insurer or provider can specify what premium or fees are required when the policy is purchased.
Policy-term cost
Reviewing the complete premium and applicable billing charges gives more context than a single installment.
Coverage effective time
Coverage is active only after the policy has been bound and its effective date and time have begun. Proof of insurance is evidence of coverage.
Why Insurance Can Cost More for Young and New Drivers
Teen and newly licensed drivers generally have less driving experience. NHTSA reports that novice teen drivers are twice as likely as adult drivers to be involved in a fatal crash, and identifies inexperience and immaturity as important contributors to teen crash risk. [4]
That evidence specifically concerns teen drivers and should not be treated as a statistic for every young adult. For young adults more broadly, auto insurance pricing can also reflect age or driving experience where permitted, driving record, vehicle, garaging location, mileage, coverage selections, deductibles, prior insurance history, and other state-permitted rating factors.
Pricing can change as driver information and insurer rating inputs change, but the result varies by insurer, state, and individual profile.
Frequently Asked Questions
Which insurance company is cheapest for young drivers?
No company is cheapest for every young driver. Pricing varies with driver information, location, vehicle, household arrangement, coverage, deductibles, discounts, and insurer rating rules. Equivalent quotes from different insurers can produce different prices.
Is it cheaper to add a young driver to a household policy?
A household-policy arrangement can be useful to compare when the young driver is eligible, but it is not automatically the lowest-cost option. A separate policy may produce a different result depending on vehicle ownership, residence, insurer rules, coverage, and other rating factors.
Can a young driver get a quote before buying a car?
Yes. Quotes or estimates may be available using vehicle information before purchase. The exact year, trim, and VIN can produce a more vehicle-specific quote when the provider supports that information.
Which discounts may be available to young drivers?
Depending on the insurer and state, examples may include good-student, qualifying driver-training, student-away, multi-vehicle, multi-policy, low-mileage, or telematics programs. Eligibility and documentation requirements vary.
Can a higher deductible reduce the premium?
A higher collision or comprehensive deductible may reduce the premium. When the deductible applies, the policyholder’s portion of the eligible covered loss is higher or the insurer’s payment is reduced according to the policy.
Can a coverage lapse affect future insurance pricing?
Depending on the insurer and state, prior coverage history or a lapse may affect eligibility, pricing, or initial payment requirements. Replacement coverage should be bound and its effective date and time should begin before prior coverage ends if continuous insurance is required.
Can telematics increase a young driver’s rate?
Some usage-based insurance programs can use driving results in premium calculations. Whether driving data can raise, lower, or otherwise affect pricing depends on the insurer, program, state rules, and the terms disclosed to the participant.
Final Thoughts on Cheap Car Insurance for Young Drivers
The lowest first payment is not necessarily the lowest total policy cost. Quotes are easier to evaluate when they use the same drivers, vehicle, coverage limits, deductibles, optional coverages, discounts, and policy-term assumptions.
Young-driver pricing can be influenced by insurer choice, household arrangement, vehicle, driving record, prior coverage, mileage, discounts, coverage selections, deductibles, and other state-permitted rating factors.
Young Driver Quote Options
Use the ZIP-code form at the top of this page to continue to available third-party auto insurance quote options. Review the complete quote, provider, coverage, and policy terms before purchasing insurance.
Return to the Quote FormReferences
- [1] National Association of Insurance Commissioners, “Telematics,” updated September 1, 2026. Source ↩
- [2] National Association of Insurance Commissioners, “A Shopping Tool for Auto Insurance.” Source ↩
- [3] National Association of Insurance Commissioners, “A Shopping Tool for Auto Insurance,” 2023. Source ↩
- [4] National Highway Traffic Safety Administration, “Teen Driving.” Source ↩